A Financial Super App Built for Everyday Ethiopians
When Safaricom launched its M-PESA mobile money service in Ethiopia in August 2023, it entered a market that had been dominated by state-owned Telebirr for over two years . Yet the M-PESA Safaricom Ethiopia app has carved out a meaningful niche by focusing on what matters most to users: simplicity, reliability, and integration. The app consolidates core M-PESA transactions, Safaricom account management, and everyday utilities into a single interface, positioning itself as more than just a wallet. It's a comprehensive financial tool designed for a population where traditional banking remains out of reach for many. With over 5.2 million active subscribers as of the 2026 fiscal year, the app has proven that there's room for competition in Ethiopia's rapidly digitizing economy .
Core Features: What the App Actually Delivers
The Google Play listing outlines a robust feature set that covers the essentials of daily financial life:
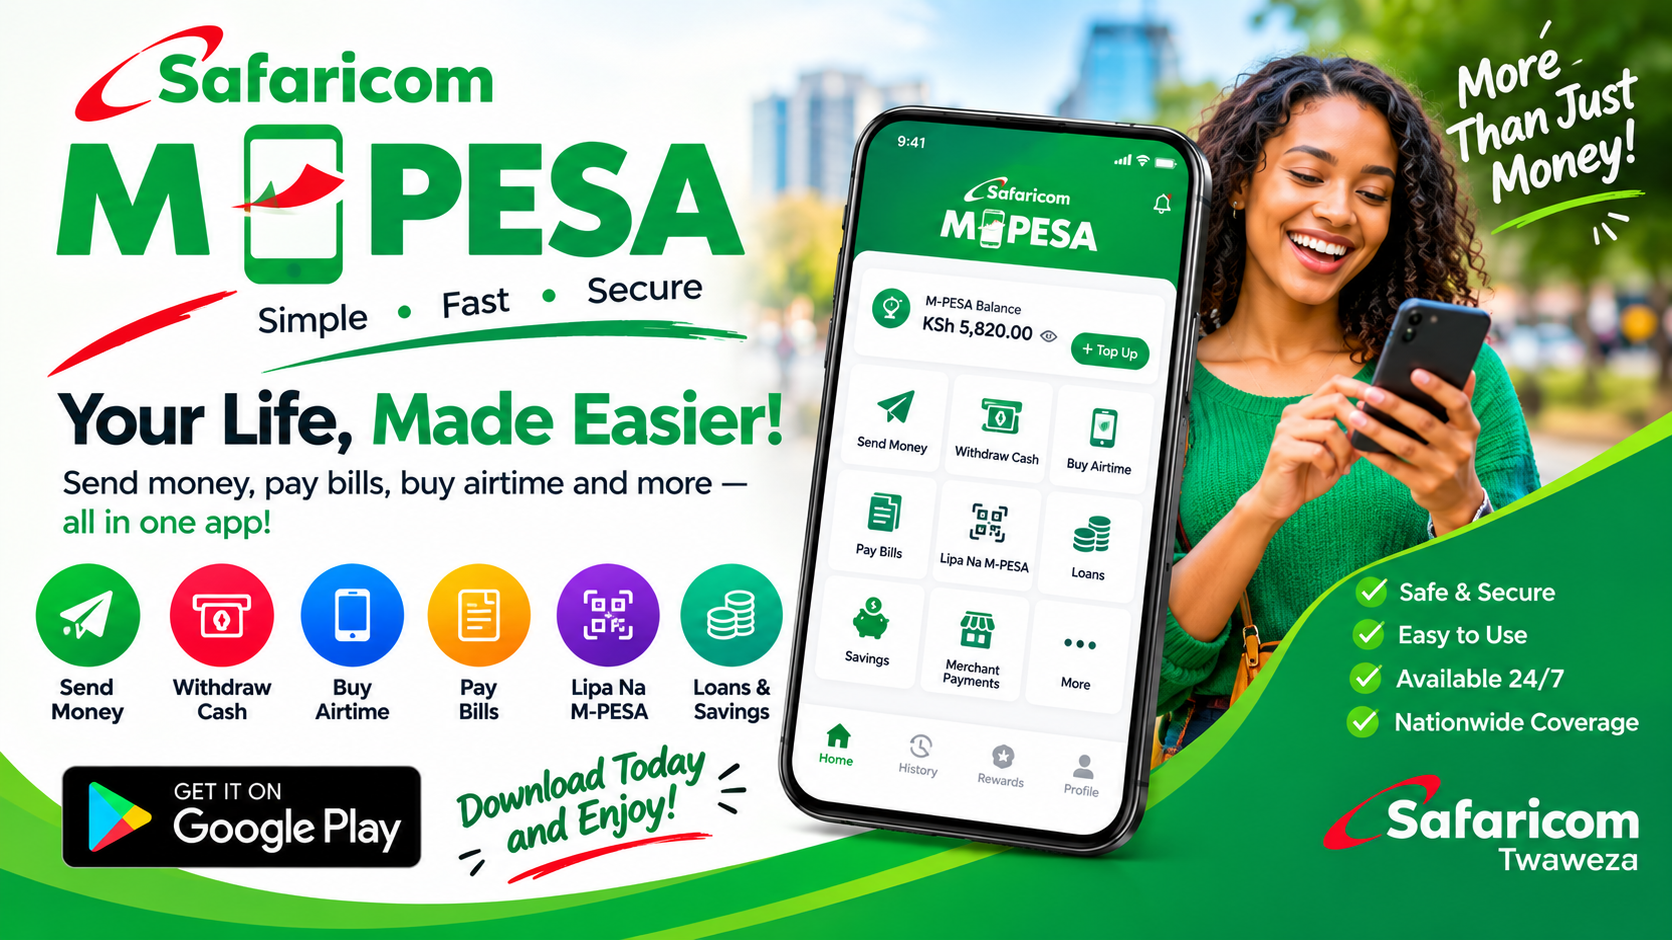
- Core M-PESA Transactions: Send money, pay merchants and bills, withdraw at agents or ATMs, and buy airtime — all with a simplified experience
- Safaricom Account Management: Check airtime, voice, and internet balances; top up; buy bundles; and even retrieve your PUK code
- Offline Mode: Log in and transact without an active data connection, a crucial feature for users in areas with unreliable connectivity
- Statements and Receipts: View, filter, download, and export M-PESA statements in PDF format, and share e-receipts for transactions
- My Spend: Track your monthly spending with aggregate totals, daily averages, and category breakdowns you can customize
The offline mode deserves special attention. In a country where network coverage can still be inconsistent outside major cities, the ability to send money, pay bills, or withdraw cash without a live data connection removes a significant barrier to adoption .
Biometric Authentication and Security: Convenience Without Compromise
One of the app's most user-friendly features is its biometric authentication system. Users can log in and authorize transactions using face or fingerprint recognition, eliminating the need to manually enter their M-PESA PIN every time . This is more than just a convenience — it's a meaningful security upgrade. PINs can be observed, guessed, or shared; biometrics are far harder to compromise. The app also incorporates QR code functionality, allowing users to initiate send-money, pay-merchant, and withdraw transactions by scanning codes, and to generate their own personal QR code for receiving payments . The combination of biometrics and QR codes makes the app both faster and more secure than traditional USSD-based transactions, which require memorizing codes and typing on small keypads.
The Safaricom Ecosystem: Managing More Than Just Money
What sets the M-PESA Safaricom Ethiopia app apart from a standalone wallet is its integration with Safaricom's broader telecommunications services. Users can check their airtime, voice, and data balances, purchase bundles, and monitor their consumption — all from within the same app where they manage their finances . This consolidation eliminates the need to juggle multiple apps or dial USSD codes for basic account management. The app also includes a "Frequents and Favorites" feature that automatically generates a list of people and businesses you transact with most often, and lets you save them for quick access . For anyone who regularly sends money to the same few people — family members, regular merchants, service providers — this small feature saves meaningful time over the course of a month.
Interoperability and Integration: Connecting to the Wider Financial System
A major milestone for M-PESA Ethiopia came in October 2025, when the platform integrated with EthSwitch, Ethiopia's national payment network . This integration established full interoperability between M-PESA and more than fifteen domestic banks and mobile wallets. What does this mean in practice? M-PESA users can now send money directly to bank accounts connected to EthSwitch, and bank customers without M-PESA accounts can transfer money to M-PESA wallets or pay M-PESA merchants by scanning EthQR codes through their banking apps . The significance of this cannot be overstated. Before this integration, moving money between mobile wallets and bank accounts was often a cumbersome process. Now, the barriers between Ethiopia's formal banking system and its mobile money ecosystem are dissolving. M-PESA also expanded its international remittance capabilities through partnerships with Dashen Bank and CashGo, allowing Ethiopians to receive money directly from abroad into their M-PESA wallets .
The Competitive Landscape: M-PESA vs. Telebirr
No discussion of M-PESA in Ethiopia is complete without acknowledging its primary competitor: Telebirr, the state-backed mobile money platform operated by Ethio Telecom. Telebirr launched in May 2021 with a significant head start — Safaricom's mobile money license was held back until August 2023, by which point Telebirr had already amassed roughly 36 million users . By the end of 2025, Telebirr counted 58.61 million subscriptions, while M-PESA Ethiopia had 5.2 million active users as of March 2026 . The gap is substantial. Telebirr benefits from being embedded in government services, from tax payments to university fees, and from Ethio Telecom's massive distribution network . Yet M-PESA's trajectory is impressive in its own right: active subscribers grew 119.4% year-over-year, and transaction volume surged 168.7% to 442.2 million transactions . M-PESA is not winning the overall market, but it is building a loyal and growing user base by focusing on user experience, interoperability, and features like offline mode that address real pain points.
Challenges and User Feedback: Where the App Falls Short
User reviews of the M-PESA Safaricom Ethiopia app present a nuanced picture. On aggregator sites, the app holds a rating around 4.5 stars across tens of thousands of reviews, with users praising its ease of use, speed, and convenience . Common positive themes include "easy to use and user-friendly," "fast and reliable performance," and "makes daily tasks easier." However, the cons are consistent: intermittent outages, occasional service interruptions, and slowdowns after extended use . These reliability issues are not unique to M-PESA — any mobile money platform serving millions will have occasional technical problems — but they matter for an app that people depend on for daily transactions. Safaricom Ethiopia has also faced broader customer frustration over data package pricing and network performance, though those complaints are separate from the M-PESA app itself . For users considering the app, the takeaway is straightforward: it's a powerful and convenient tool, but like any digital service, it's not immune to technical hiccups.
The Verdict: A Powerful Tool in Ethiopia's Digital Economy
The M-PESA Safaricom Ethiopia app is not just a wallet — it's a statement of intent. Safaricom has invested heavily in Ethiopia and is playing a long game, building infrastructure, partnerships, and user trust even as it competes against a state-supported incumbent. For users, the app delivers genuine value: offline transactions, biometric security, bank interoperability, and a clean, functional interface that makes everyday financial tasks easier. The competition with Telebirr has been good for consumers, forcing both platforms to improve. If you're a Safaricom user in Ethiopia — or anyone looking for a flexible mobile money solution that works across networks — the M-PESA app is worth downloading and exploring. It may not have Telebirr's sheer scale, but it has features, polish, and a clear trajectory that make it a serious contender in Ethiopia's rapidly evolving financial landscape.